SAN DIEGO HOUSING • OCTOBER 14, 2026
Buy, Sell or Wait? Let’s Navigate the San Diego Housing Market.
If you follow the news or look online, you might think the San Diego housing market has come to a standstill. Is that true?
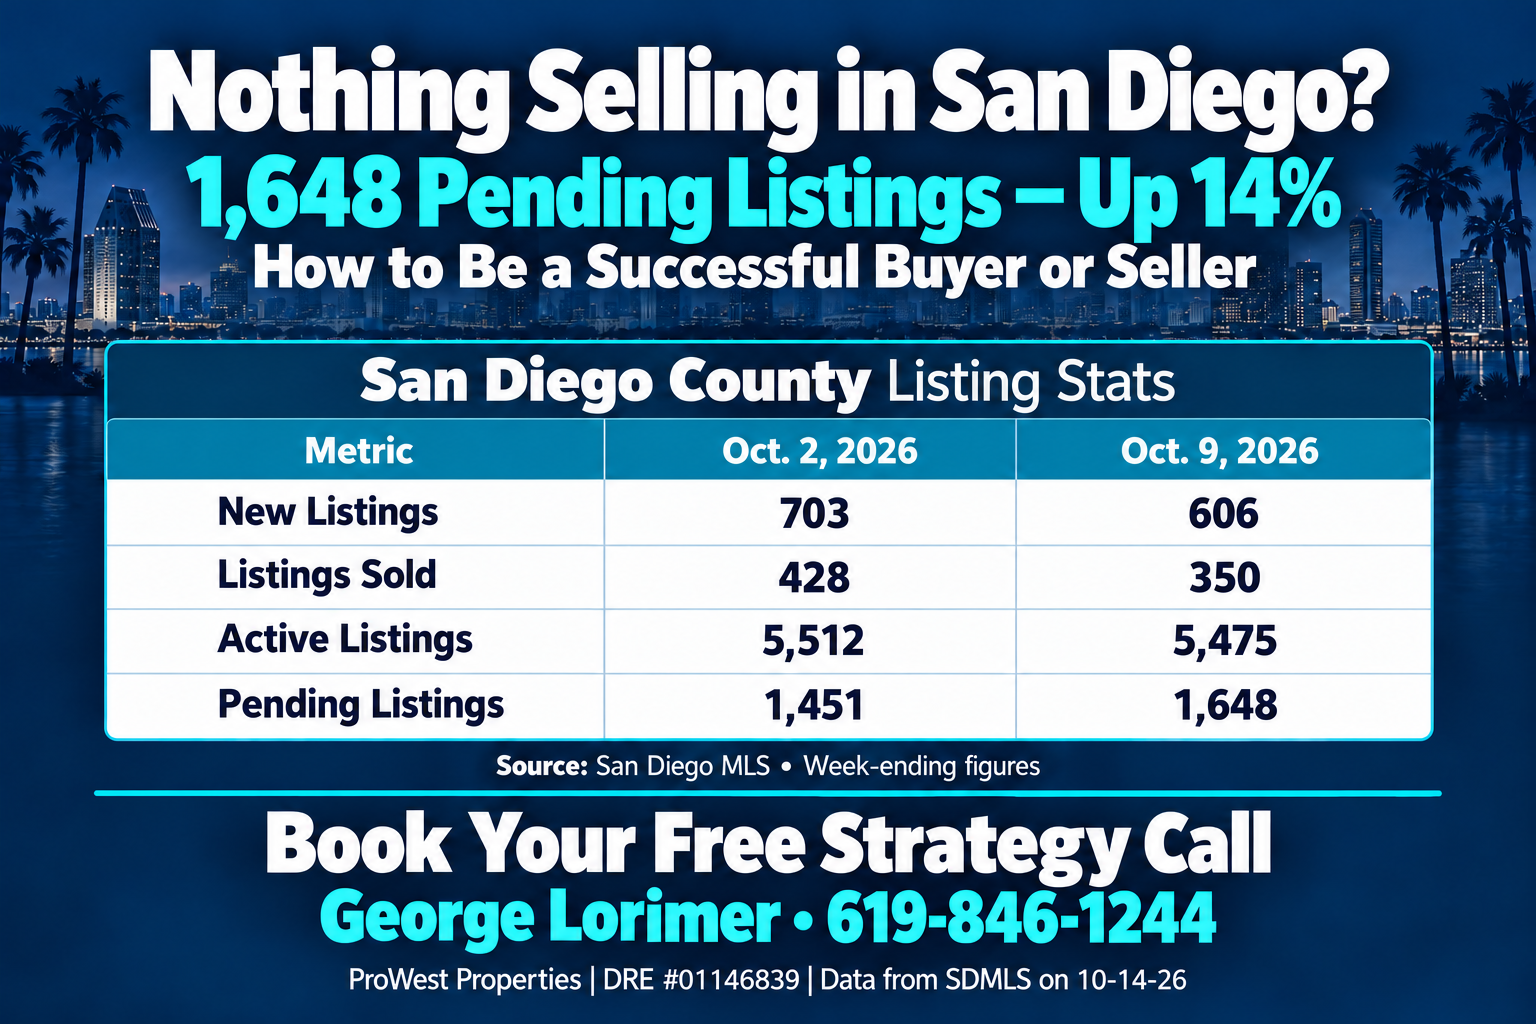
Did you know that 1,648 San Diego County listings are pending—in escrow? That’s a lot of moves underway this fall!
Is it easy? NO.
Is there opportunity? BIG TIME.
If you’re wondering whether to buy or sell now—or wait—the answer starts with your situation and a workable plan.
Homes are still selling. Buyers are still buying. You need a strategy to navigate this market.
That’s why I made that silly graphic of me in a captain’s hat—to help you navigate it. LOL.
The Market Is Moving
San Diego MLS’s report for the week ending October 9, 2026, shows:
- 350 listings sold, compared with 428 the previous week.
- 1,648 pending listings, up from 1,451—an increase of approximately 14%.
- 5,475 active listings, giving buyers options.
Closed sales slowed that week, but hundreds of homes still sold. Pending listings increased, too. The opportunity is there—we have to find the right route for you.
Source: SDMLS data supplied on 10-14-26, comparing weeks ending October 2 and October 9. Pending figures represent listings in escrow, not newly accepted offers that week.
Buyers: Two Ways to Get a Lower Mortgage Rate
1. Get a Rate Buydown
A seller or builder credit may help pay for a lower mortgage rate. For example, a permanent buydown could reduce a rate from 7.5% to 5.99%, depending on lender pricing, available credits and your qualifications.*
A permanent buydown lowers your loan’s interest rate. A temporary buydown reduces payments for a limited period. We’ll compare the cost and terms so you understand what happens after closing.
2. Find a Home With an Assumable Loan
Some homes have existing assumable loans with rates in the 2%–4% range. An approved buyer may be able to take over the remaining loan balance at that existing rate.*
You still need to cover the difference between the purchase price and the loan balance. If you need additional financing, that payment can reduce the savings. Seller cooperation, approval and closing time also matter.
Let’s compare the total payment and cash required—not just the headline rate.
Sellers: Avoid These Two Mistakes
1. Selling Without a Plan for Your Next Home
Where will you go? How will you coordinate your sale and purchase?
That’s the real estate Catch-22: you don’t want to sell without somewhere to live, or buy first and get stuck with two homes and two mortgages.
Let’s review options such as buying before you sell, negotiating a rent-back or arranging temporary housing.* Start with your expected sale proceeds, your next-home budget and a realistic timeline.
2. Holding Onto a Price Buyers Are Rejecting
“But the comparable sale was higher.”
“But Zillow says…”
“But another agent said it was worth more.”
Those are reference points. Today’s buyers decide whether your home offers enough value compared with their other choices.
If showings are scarce or offers aren’t coming, review your price, presentation, marketing and showing access. When those other pieces are working, price is often the adjustment needed.
Look at the homes that are selling. How can yours become the better choice?
Show better. Price competitively. Give buyers a reason to choose your home.
Want a fresh perspective on your home’s price, competing listings and what it will take to sell? Text me at 619-846-1244.
When Does Waiting to Buy Make Sense?
If you expect to move within three years: buying and selling costs can make a short ownership period expensive. Compare renting with buying before committing. Three years is a starting point for the discussion, not a guarantee of a financial payoff.
If you cannot qualify for an affordable loan yet: make a plan to improve your income, credit or savings. But get the facts from a lender before assuming you cannot qualify.
One mistake I see is qualified buyers waiting because they cannot afford their ideal home. Years pass, and they may get further from their goal if home prices rise faster than their income and savings.
Consider buying a home or condo you can comfortably afford today to get your foot in the door. Your first home does not have to be your forever home.
Keep cash reserves and budget for taxes, insurance, repairs and HOA dues. Paying down your mortgage can build equity, but your plan should work without relying on appreciation or a future refinance.
Popular Home Searches
Explore homes by area and budget, then tell me which options fit your plans.
Let’s Map Out Your Next Move
Whether you want to buy a home and start building equity or sell and put your equity to work, we can build a plan around your budget, timing and goals.
Book Your Free Strategy Call Text George Lorimer: 619-846-1244 Call 619-846-1244Want the bottom-line numbers? Text “BUY” or “SELL,” your preferred area or property address, and your timeline.
George Lorimer
Your Home Sold Guaranteed, or I'll Buy It!*
Call/Text: 619-846-1244
ProWest Properties | DRE #01146839 | *Conditions apply
Data from SDMLS on 10-14-26
*Conditions apply. Guarantees and selling programs are subject to eligibility, availability and applicable terms. Not all homes qualify. Mortgage rates shown are illustrative, not current quotes or guaranteed offers. Actual rates, APR, costs, seller-credit limits and eligibility vary. Assumable rates apply to the remaining existing loan balance; additional financing may carry a different rate. Home values can decline. Market figures reflect the supplied SDMLS report comparing weeks ending October 2 and October 9, 2026.